Riester-Rente tax: how your payout is taxed
Published on · Publisher and Managing Director, Alsterspree Verlag
This article was written by an author with the support of AI.
Riester-Rente or AVD - which fits you?
A free, no-obligation conversation with an adviser from our independent network of 1,000+ vetted advisers.
How is the Riester-Rente taxed in retirement?
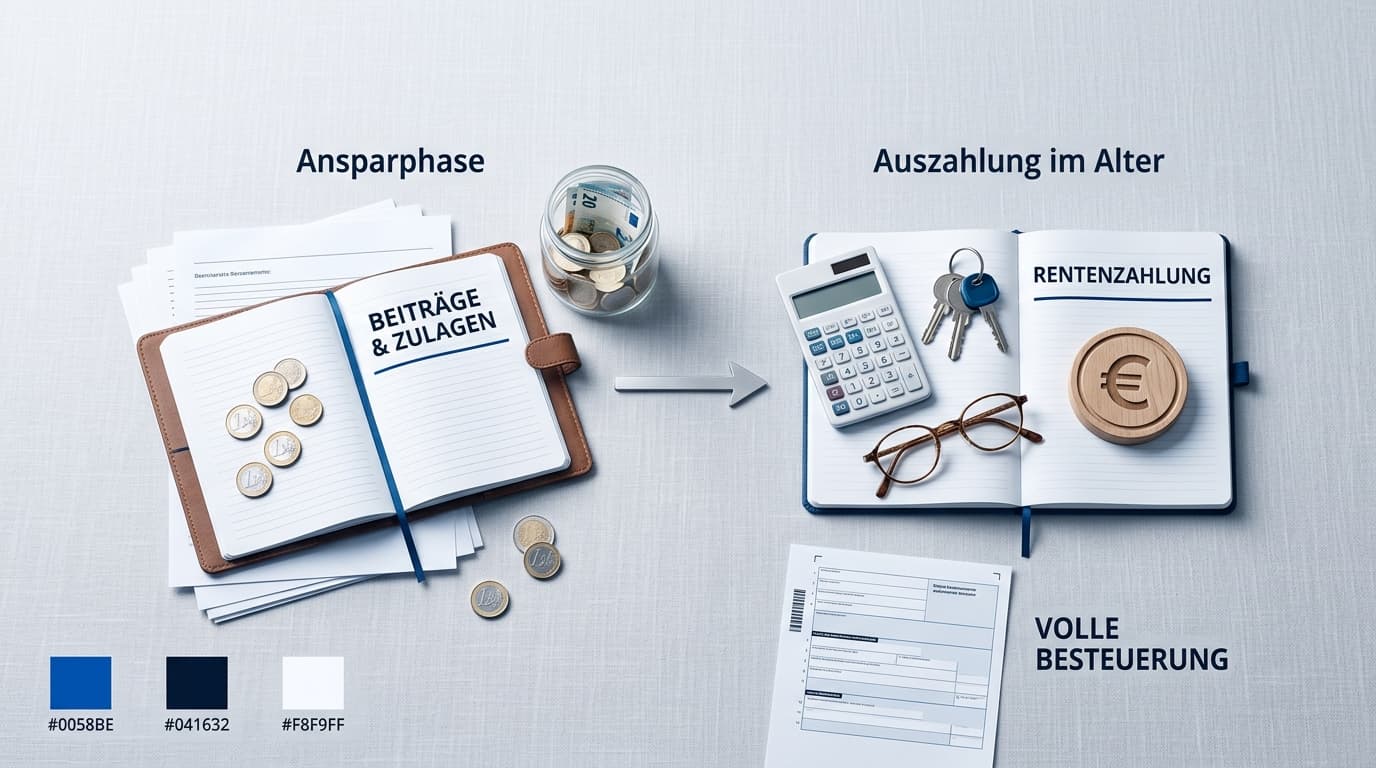
Yes, the Riester-Rente is taxed in retirement. Benefits from subsidised Riester capital count as other income (sonstige Einkünfte) under § 22 Nr. 5 EStG and are taxable in full, at your personal tax rate in each year of payout[1]. The principle behind this is called deferred taxation: because your contributions were made tax-free during the accumulation phase through allowances and, where applicable, a Sonderausgabenabzug (deduction as a special expense), tax only applies when the money is paid out[2].
It is not only the subsidised contributions you paid yourself that are taxed in full. All portions derived from allowances, and from income and capital gains earned, are equally taxable[1]. The Riester subsidy is therefore not a tax exemption but a tax deferral: the state forgoes tax during the accumulation phase and collects it only in retirement.
- Subsidised own contributions, to the extent they were subsidised by an allowance or the Sonderausgabenabzug
- The retirement savings allowances you were granted, meaning the Grundzulage (the basic state allowance) and the Kinderzulage (the child allowance)
- Income and capital gains from the investment during the accumulation phase
The tax rate, on the other hand, works in your favour: in retirement your personal tax rate is as a rule lower than during your working life, because your pension is smaller than your income during your earning years[2]. This effect is the real advantage of the tax deferral. Bear in mind, though, that large capital payouts can also push up your tax rate in the year concerned, a point that matters for the partial payout.
What applies to unsubsidised contributions?
Not all Riester capital is fully taxable. Contributions are unsubsidised if you were entitled neither to an allowance nor to a tax benefit from the Sonderausgabenabzug for them: payments above the maximum of 2,100 euros, which includes the allowances, and contributions from contribution years in which you were not among the eligible group of people[3].
Unsubsidised capital is not taxed in full, only in part. How it is taxed depends on the type of benefit; as a general rule, only the Ertragsanteil is taxed[1]. With a lifelong pension from unsubsidised capital, only the Ertragsanteil of the annual pension is taxable and the rest remains tax-free. The Ertragsanteil depends on the age you have completed when the pension starts, and it falls the later the pension begins; the applicable percentages are set out in the table in § 22 Nr. 1 Satz 3 Buchstabe a Doppelbuchstabe bb EStG[4].
| Age completed at start of pension | Taxable Ertragsanteil |
|---|---|
| 60 to 61 years | 22 % |
| 65 to 66 years | 18 % |
| 67 years | 17 % |
For forms of benefit other than a lifelong pension, such as a drawdown plan or a one-off payment from unsubsidised capital, as a general rule only the investment return is taxed. For Riester insurance policies, the rules for endowment life insurance apply (§ 20 Abs. 1 Nr. 6 EStG); for other contracts, the difference between the benefit and the total contributions paid in is taxable[1]. If you have made both subsidised and unsubsidised contributions, the resulting benefits are split accordingly in the payout phase[1]. This does not change the full tax liability on your subsidised portions; the split concerns only the unsubsidised contributions.
How is the partial payout taxed?
At the start of the payout phase, you can have a lump sum of up to 30 percent of your Riester capital paid out; the remainder goes into the lifelong Riester-Rente paid monthly[2]. You have to pay tax on this lump sum in full, in the year you receive it[2]. The partial payout is one of the payout forms permitted under the certification rules: up to 30 percent of the capital available at the start of the payout phase may be paid out separately from the monthly benefits (§ 1 Abs. 1 Satz 1 Nr. 4 AltZertG).
The tax catch lies in progression. The lump sum increases your taxable income for the year of payout, and the higher the lump sum and your other income in that year, the stronger this effect. How it plays out in an individual case depends on your tax bracket and cannot be quantified in general terms.
- Partial payout: a permitted form of payout; the lump sum is taxed in full in the year it is received[2]
- Monthly pension: correspondingly lower after the lump-sum payment[2]
- Full payout: counts as a schädliche Verwendung (non-qualifying use); the entire state subsidy has to be repaid and the income it contains is taxable[2]
Whether a partial payout pays off for you depends on the size of your capital, your tax rate and your other income in the year of payout. This article cannot carry out that individual assessment; your provider's product information sheets and contract documents, as well as individual advice, will give you reliable answers here.
Are health insurance contributions due on the Riester-Rente?
Health and long-term care insurance contributions may be due on your Riester-Rente, but it depends on your insurance status. Members of statutory health insurance who are compulsorily insured do not have to pay contributions on payments from a Riester contract; voluntarily insured members, by contrast, are liable for contributions to statutory health and long-term care insurance[5].
Statutory pensioners are usually compulsorily insured through the Krankenversicherung der Rentner (KVdR, the statutory health insurance scheme for pensioners). Whether you belong to this group in retirement depends, among other things, on your prior insurance period. Clarify your status with your health insurer early, because it determines how much the contributions reduce your net pension from the Riester contract.
- Consequence: voluntarily insured members should factor in the effect of contributions when calculating their net pension
Note that your provider's benefit statement (Leistungsmitteilung) does not help here. It is a tax certificate covering the benefits received in the calendar year and contains no information on health or long-term care insurance contributions.
Where do you enter the pension in your tax return?
You enter benefits from your Riester contract in Anlage R-AV/bAV (the tax return schedule for private and occupational pension benefits). This is where benefits and pensions from domestic retirement savings contracts and from occupational pension schemes are declared, including those from Riester contracts[6]. The basis is the information from your provider: when you first receive benefits, and whenever the benefit to be paid in the calendar year changes, the provider must notify you separately of the benefit amount received, electronically if you agree[1].
This benefit statement is your working document for the tax assessment. It shows the amount you received in the past calendar year and therefore forms the basis for taxation as other income.
- Wait for your provider's benefit statement; it is issued after the end of the calendar year, electronically on request
- Transfer the figures to Anlage R-AV/bAV, together with any income-related expenses (Werbungskosten)[6]
- Can you skip the schedule? According to the ELSTER (the German tax authorities' online filing portal) guidance on the 2025 income tax return, Anlage R-AV/bAV is not required if the data were transmitted electronically and your income-related expenses do not exceed the flat-rate allowance of 102 euros[6]
Do not confuse it with Anlage AV (the schedule for claiming tax relief on contributions): it is used for the tax subsidy on contributions during the accumulation phase and has nothing to do with the taxation of the payout[6]. Note also that the line numbers on the forms differ from one assessment year to the next; the rules given here follow the guidance for the 2025 assessment year.
Is the Altersvorsorgedepot taxed differently?
No. The Altersvorsorgedepot follows the same deferred taxation as the Riester-Rente: in the payout phase, benefits are taxed at your individual tax rate under § 22 Nr. 5 EStG, and no taxable investment income arises during the accumulation phase. Tax is therefore no argument for switching: both systems treat your retirement benefits the same way for tax purposes.
- Taxation: identical to the Riester-Rente, deferred under § 22 Nr. 5 EStG
- Accumulation phase: income and gains remain tax-free
- Switching costs: in the first five years after the contract is concluded, at most 150 euros charged by the outgoing provider, free of charge thereafter; the receiving provider may charge a one-off administration fee of at most 150 euros
- Form of payout: a choice between a lifelong life annuity and a fixed-term drawdown plan that runs at least until you turn 85
- Switching provider: also possible at the start of the payout phase, for example to a provider with a pure payout product
For your decision, then, what counts are costs and the form of payout, not tax. A separate guide explains which switching costs arise in detail and how the transfer value is calculated. We have set out separately how the taxation of the Altersvorsorgedepot works in detail across its three phases.
If you want to check which provider suits your preferred form of payout and cost expectations, compare account providers with the Vorsorgedepot-Lotse provider comparison: a neutral, criteria-based comparison of neobrokers and Altersvorsorgedepot providers, including direct account-opening links. All information in this article is based on sources and is for general information only; it does not constitute tax advice or investment advice in an individual case (not investment advice within the meaning of § 1 Abs. 1a Nr. 1a KWG).
Frequently asked questions
- Does the Riester-Rente have to be taxed?
- Yes. Riester benefits are subject to deferred taxation: contributions were made tax-free during the accumulation phase, and in return the payouts are taxable as other income under § 22 Nr. 5 EStG. Subsidised benefits are taxed in full at your personal tax rate, including the allowances, income and capital gains.
- How much tax is due on the Riester-Rente?
- The tax base is the annual amount of the benefit, and your personal tax rate in the year of payout applies. Because income in retirement is usually lower than during working life, the tax rate is in many cases below the rate you paid back then. Specific tax amounts can only be calculated individually and should only be stated together with the calculation and its source.
- Are health insurance contributions due on the Riester-Rente?
- For members of statutory health insurance who are compulsorily insured, for example through the KVdR, benefits from a Riester contract are free of contributions. Voluntary members of statutory health insurance, by contrast, are liable for contributions to statutory health and long-term care insurance and should allow for these contributions when planning their net pension.
- Where do I enter the Riester-Rente in my tax return?
- The benefits go in Anlage R-AV/bAV of your income tax return. The basis is your provider's benefit statement; the provider also reports the amounts electronically to the tax authorities as a pension receipt notification (Rentenbezugsmitteilung) (§ 22a EStG). If the data were transmitted and your income-related expenses do not exceed the flat-rate allowance of 102 euros, you can leave out the schedule (2025 assessment year).
- How is a partial payout of the Riester-Rente taxed?
- At the start of the payout phase, you can have a lump sum of up to 30 percent of your Riester capital paid out. You have to pay tax on this amount in full in the year of payout. Because the lump sum is assessed together with your other income for the year, it may increase your personal tax rate in the year you receive it (progression effect).
- Is the Altersvorsorgedepot taxed the same way as the Riester-Rente?
- Yes. Benefits from the Altersvorsorgedepot are also taxed on a deferred basis under § 22 Nr. 5 EStG at your individual tax rate. No taxable investment income arises during the accumulation phase; capital gains and income are only taken into account in the payout phase. For tax purposes, there is therefore no difference between the two products.
- What are the tax consequences of a non-qualifying use?
- In the event of a schädliche Verwendung (non-qualifying use), such as a full payout of the capital or residence outside the EU and EEA from the start of the payout phase (§ 95 EStG), the allowances and tax benefits granted have to be repaid. After the allowances are deducted, the assets count as a benefit, and in the end it is the income they contain that is taxed.
Sources
- [1]finanzamt.nrw.de
- [2]riester.deutsche-rentenversicherung.de
- [3]gesetze-im-internet.de
- [4]gesetze-im-internet.de
- [5]bmas.de
- [6]elster.de
- []Do I have to pay tax on gains in the Altersvorsorgedepot?
- []What does switching from Riester to the Altersvorsorgedepot cost?
- []How is the Altersvorsorgedepot taxed?
- []Kriteriengestützten Anbietervergleich
Riester-Rente or AVD - which fits you?
Wondering whether switching to the AVD makes sense? Let's work it out together.
Free and without obligation. Advice from an adviser in our independent network of 1,000+ vetted advisers.